Physical vs. Virtual Cards: It’s Not an Either-Or Decision
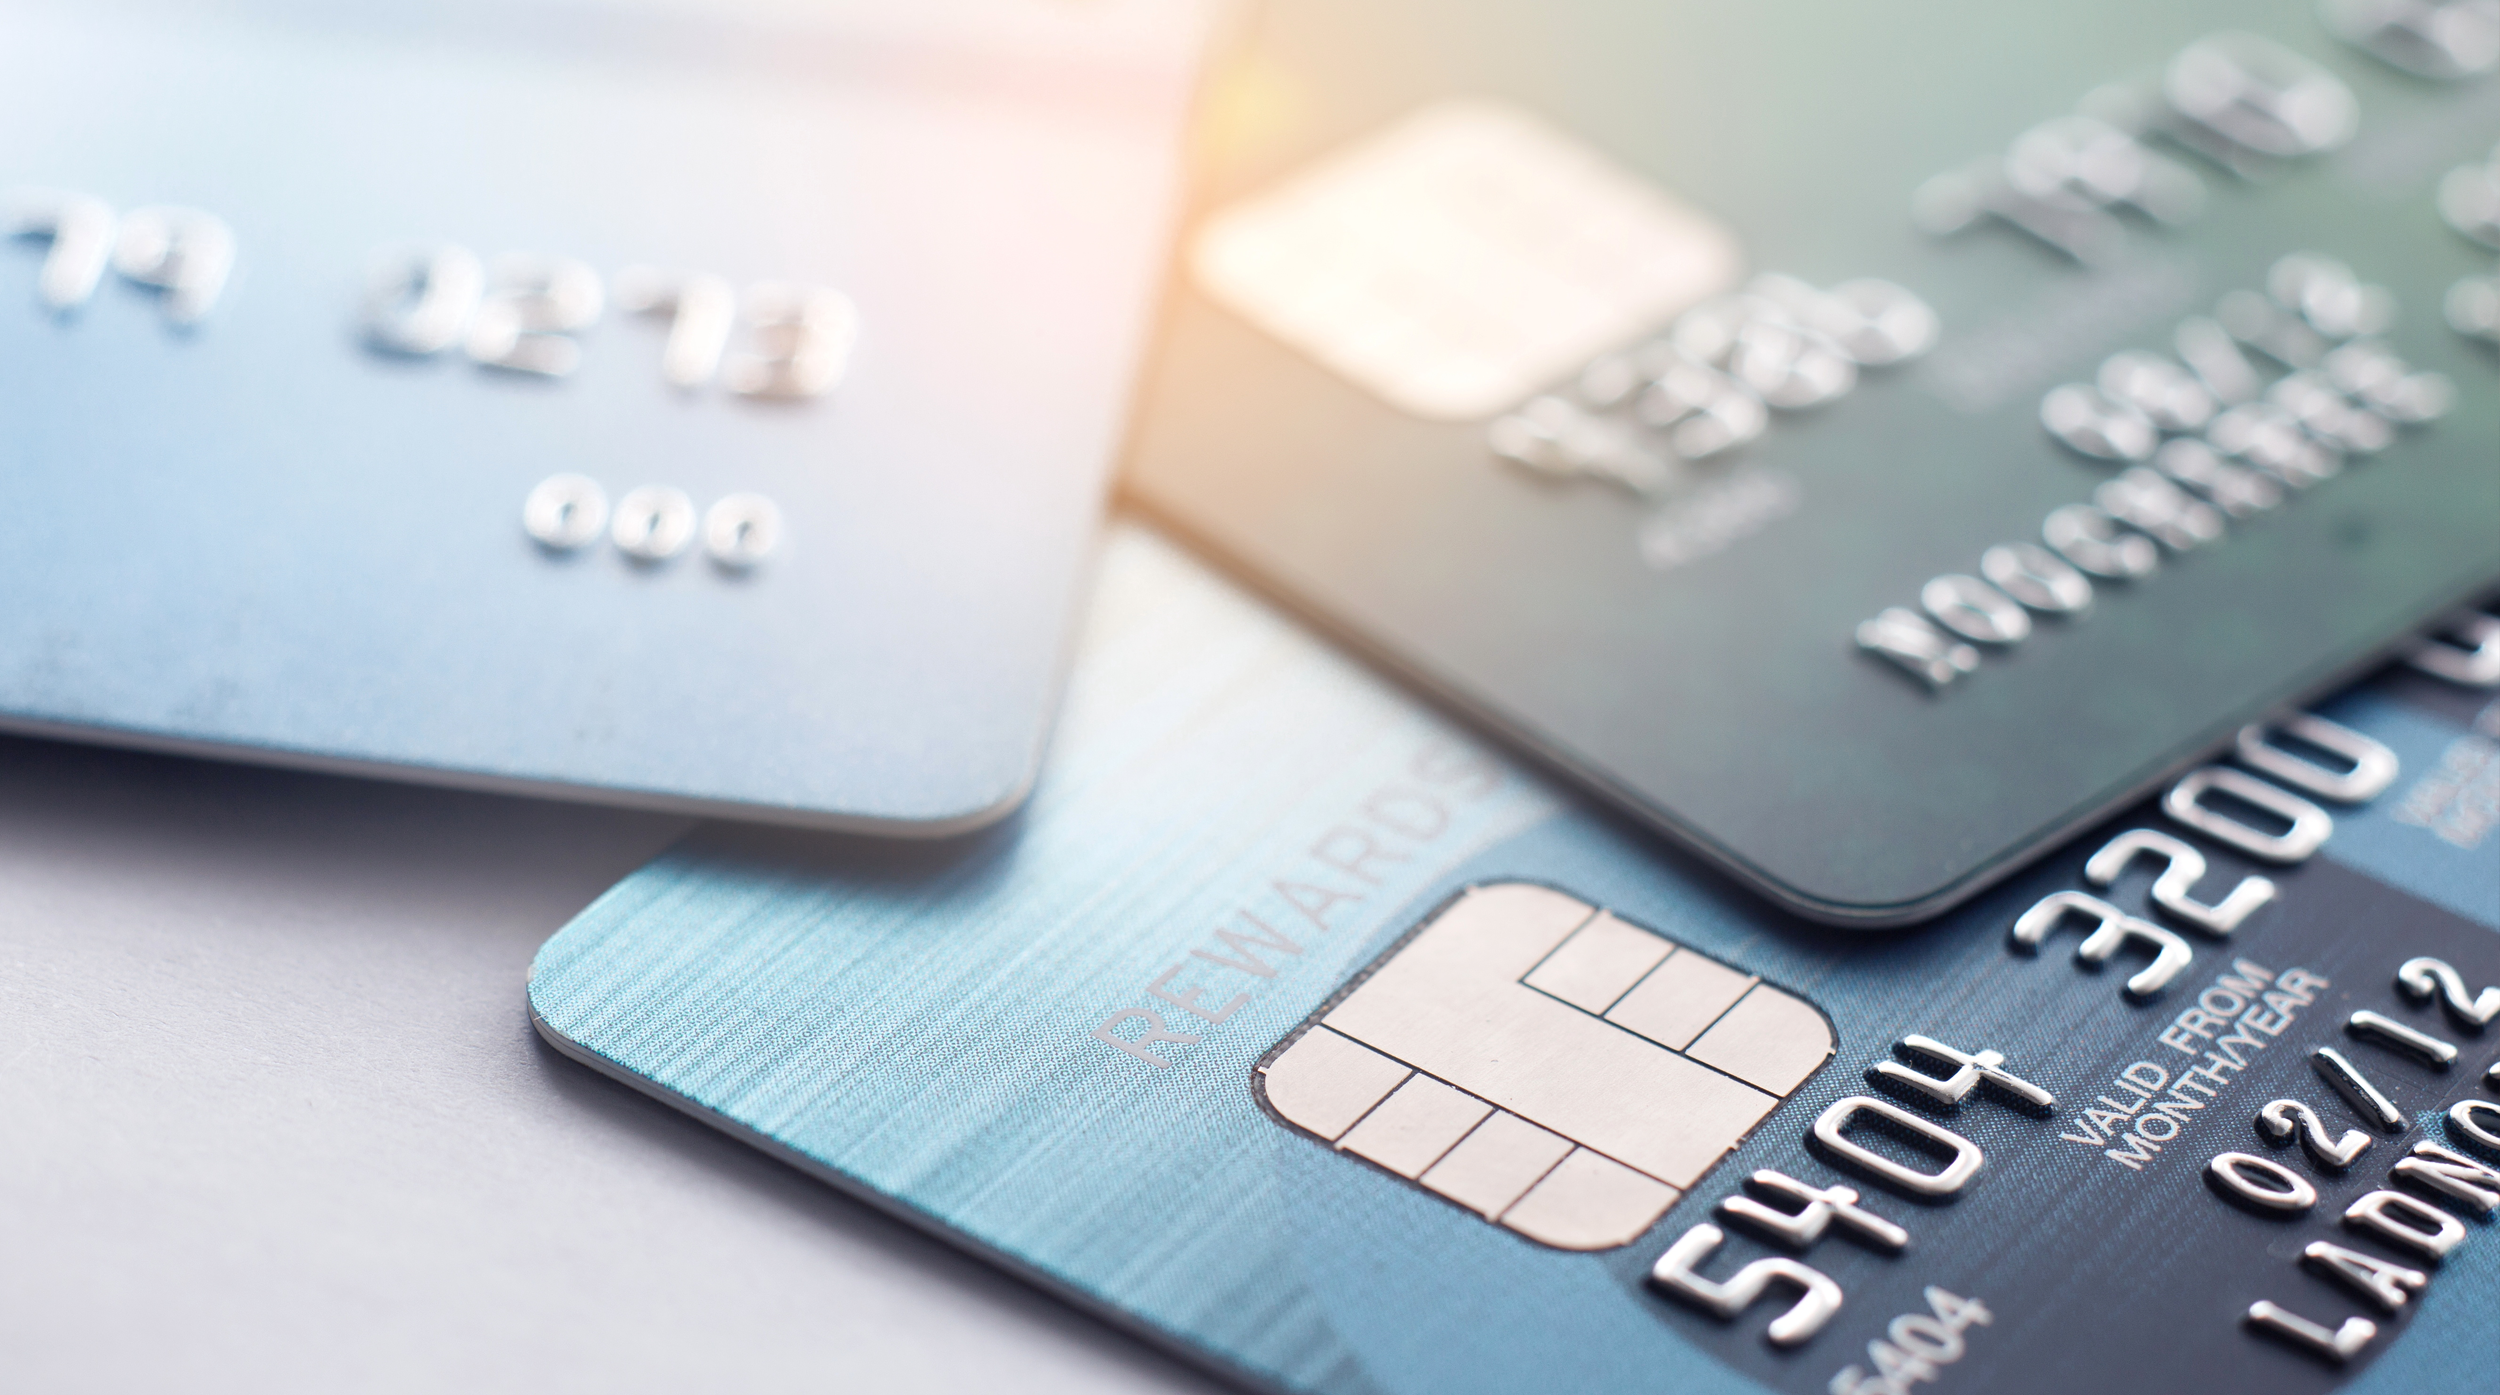
Most people still picture a physical card when they think about paying for something. While that image is still accurate, it is becoming less complete every year as virtual cards become increasingly popular.
Virtual cards are not new. What has changed is their role within the card program. Once concentrated in specific commercial payment use cases, virtual issuance is increasingly becoming a core capability across commercial, consumer, and prepaid programs.
What a Virtual Card Actually Is
A virtual card is a payment card that exists digitally rather than physically. It carries the same core components as a traditional card — a card number, an expiration date, and a CVV — but it never takes a physical form. It lives in a system, a digital wallet, or an app, and it can be issued, used, and canceled entirely without a piece of plastic ever being produced.
That might sound like a simple distinction, but it has significant operational implications. A virtual card can be:
• Generated in seconds.
• Configured for a single transaction or a defined spend window.
• Canceled instantly without affecting any other card or account.
• Built with controls that physical cards cannot — spend limits by category, by vendor, by amount, or by time.
The result is a payment instrument that is faster to deploy, easier to manage, and more precise in how it operates than its physical counterpart.
Why the Shift Is Happening Now
Virtual cards have been available to enterprise finance teams for years, primarily through commercial card programs designed for accounts payable workflows. But three forces are now pushing adoption well beyond that original use case.
The first is speed. Businesses and consumers increasingly expect to be able to use a card the moment it is approved, not after waiting several days for plastic to arrive in the mail. Instant issuance to a digital wallet closes that gap, allowing cardholders to use their card in the first week and build better card-use habits while the excitement of approval is still fresh.
The second is security. Every physical card that exists is a potential point of compromise. A virtual card issued for a single transaction reduces that risk. Once the transaction is complete, the card number is no longer valid, and there is nothing to steal, copy, or counterfeit. For businesses managing high volumes of vendor payments or one-time disbursements, that level of control is especially valuable.
The third is operational efficiency. Managing physical cards at scale means tracking inventory, handling replacements, and absorbing the cost and delay of card production and delivery. Virtual issuance removes a significant amount of that friction. Cards can be issued programmatically, in volume, when they are needed — with less fulfillment lag and no physical inventory to manage.
Where Virtual Cards Are Being Used
The use cases for virtual cards now span nearly every card program type.
In commercial credit programs, virtual cards have become a preferred tool for accounts payable teams. Finance departments can issue a unique card number for each vendor or invoice, providing granular visibility into every transaction and eliminating the risks associated with sharing a corporate card across a team. The ability to set a specific spend limit for a specific purpose makes reconciliation faster and audit trails cleaner.
In consumer programs, virtual card issuance has become a meaningful activation tool. A cardholder who is approved for a credit card and immediately provisioned to their digital wallet is ready to spend before their physical card arrives. That first transaction can then happen sooner, and usage habits form faster.
In prepaid programs, virtual cards are particularly well suited to disbursements that need to reach recipients quickly — gig worker payouts, insurance claim settlements, employee incentives, and government benefit distributions. When speed and accessibility matter more than a physical form factor, virtual issuance is a clear path to getting funds where they need to go.
What This Means for Businesses Building Card Programs
A physical card and a virtual card are not competing options. Most modern programs offer both. But the question of virtual card capability — whether a program can issue instantly, configure card-level controls, and support digital wallet provisioning — is increasingly a baseline expectation rather than an advanced feature.
Businesses evaluating card programs should ask not just whether virtual cards are supported, but how they are supported.
• Can cards be issued programmatically?
• Can controls be set at the individual card level?
• Can issuance happen in real time?
The answers to those questions reveal a great deal about the underlying infrastructure and the sophistication of the program management model behind it.
The plastic card is not going away. But the programs that will perform best over the next several years are the ones that treat virtual issuance not as an add-on, but as a core capability, designed to serve cardholders where they already are.
Virtual cards are one piece of a modern card program built to perform from day one. If you are ready to build yours, NXTMOVES is ready to help.
Learn more at nxtmoves.io or get in touch.
Related posts
Explore the latest trends and insights at NXTMOVES.
Before You Launch a Card Program, Read This
The Most Important Role in Payments No One Talks About
How Program Management Took Over Payments